
GDP, inflation, employment: the 3 figures on Friday morning that will judge Lescure's economy

 Prefer us on Google


A high-risk Friday for Bercy and for your crypto wallet. On October 30, Insee will publish at 7:30 AM the first estimate of GDP for the third quarter and household consumption for September. Then, at 8:45 AM, the provisional inflation for October and the flash estimate of salaried employment will be released. Minister of Economy Roland Lescure is awaiting them in a heavy atmosphere. Indeed, household confidence fell to 80 in October, the lowest since June 2013. Moreover, inflation rose to 3.1% in September.
The bond market is also trembling. The 10-year OAT hit 5% on October 21, a first since 2002. Furthermore, the solemn vote on the revenues of the 2027 budget is set for Tuesday, November 3. This section includes a 31.4% tax on conversions of cryptocurrencies into stablecoins. A zero GDP or inflation above 3% would weigh on both the debate over the €54 billion effort, the yield on your savings, and the appetite for Bitcoin.
Key Points
- On Friday, October 30, Insee will publish the Q3 GDP at 7:30 AM, followed by October inflation and salaried employment at 8:45 AM.
- Insee and the Bank of France expect +0.1% growth after a second quarter at zero.
- Inflation reached 3.1% in September, while the Livret A only yields 1.7%.
- The vote on November 3 regarding the revenues of the 2027 budget includes a 31.4% tax on crypto conversions to stablecoins.
Third Quarter GDP: The French Economy Plays for Zero
Let’s start with the most anticipated figure. Both Insee and the Bank of France are betting on +0.1% between July and September. The first quarter had declined by 0.2% and the second stagnated. However, Insee initially announced +0.2% for this second quarter on July 30. It was then revised down to zero on August 28.
Private economists are not more cheerful. In an AFP dispatch on October 28, Anthony Morlet-Lavidalie from Rexecode also targets +0.1%. He sees "no growth relay today in the French economy, no engine". For her part, Charlotte de Montpellier at ING speaks of an "accumulation of signals" indicating a new stagnation. Finally, household consumption, published at the same time as GDP, had gained 0.4% in July thanks to the heatwave. It then lost 0.5% in August.
A zero or negative figure would thus shake the government forecast of 0.5% for 2026. Roland Lescure had already revised it down from 0.7% to this level on September 11. Insee, on the other hand, expects only 0.4% for the year.
October Inflation and Employment: Price Peaks Against Social Breakdown
At 8:45 AM, two figures will be released simultaneously. First, inflation: that of September was confirmed at 3.1% year-on-year on October 15, the highest since early 2024. Energy alone shows +21.3%. Rexecode considers prices "not far from the peak, even at the peak". Insee aimed for 2.9% in December in its September economic note. Thus, an October figure of 3% or less would reinforce the idea of a plateau. Conversely, a new peak above 3.1% would increase pressure on the ECB.
The ECB is precisely making its decision this Thursday, October 29. It raised its deposit rate in June and then in September, up to 2.50%. Economists surveyed by Reuters expect a pause this Thursday, followed by another increase in December.
Salaried employment completes the picture. According to Insee, the private sector lost 24,300 jobs in the second quarter and 80,900 year-on-year. Furthermore, the employment climate fell by another 3 points to 95 on October 22. A third quarter of job losses would thus fall right in the middle of the examination of the 2027 budget. The Minister of Action and Public Accounts, David Amiel, already estimates the deterioration of the deficit caused by the votes of the deputies at €10 billion.
From OAT to Livret A: What the Crypto Saver Plays on Friday
The link with the debt is direct. The 10-year OAT exceeded 5.1% on October 22. It then fell back below 5% on Monday, October 26, after Moody's maintained the Aa3 rating with a negative outlook. However, the yield rose again on October 28, to more than 150 basis points above the German Bund. A zero GDP combined with 3% inflation forms the worst cocktail for a state creditor. Tax revenues are declining, indexed expenditures are rising, and the ECB has no reason to lower its rates.
The first effect for the crypto saver comes through the real rate. The Livret A yields 1.7% since August 1, which is 1.4 points less than inflation. Each month at 3% thus eats away at risk-free savings. Therefore, Bitcoin becomes more audible as a diversification asset. However, the second effect works in the opposite direction. An OAT above 5% means a higher risk premium everywhere. Volatile assets, led by crypto, are often the first to be sold in these phases of aversion.
The calendar offers no respite. After Friday's figures, deputies will complete the examination of the revenues of the 2027 budget before the solemn vote on November 3. The amendment adopted on October 16 is part of the package. It subjects conversions of cryptocurrencies into stablecoins to the flat tax of 31.4% starting January 1, 2027. Finally, a zero GDP would reinforce the government's quest for revenues at a time when crypto holders are waiting to see if this measure will survive the shuttle.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
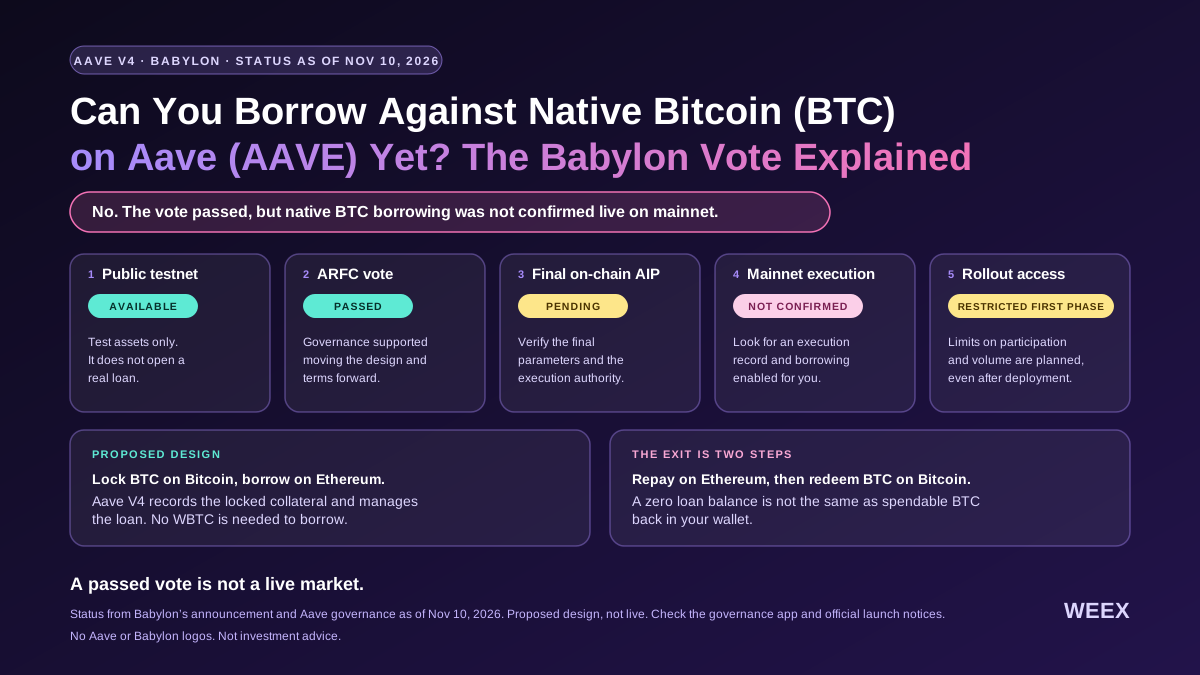
Can You Borrow Against Native Bitcoin (BTC) on Aave (AAVE) Yet? The Babylon Vote Explained
Can you borrow against native Bitcoin on Aave yet? See what the Babylon vote approved, what still needs to launch, and how BTC liquidation would work.
Kim & Chang Lawyer: "Excessive Responsibility Should Not Be Imposed on Stablecoin Issuers"
Mr&强 Analyzes Bitcoin and Ethereum Fluctuation Patterns
WEEX Exclusive:Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.
When is the launch date of Bitcoin Hyper? Testnet, tokens, and mainnet are separate milestones
Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.
Bitcoin non-empty wallets drop by 108700 amid retail capitulation
LNbits disables hosted Bitcoin services with no restart timeline
Bitcoin Spot ETF Sees Net Outflow of $201 Million for Three Consecutive Days
Ray Dalio Warns of Diminished Trust in U.S. Treasuries Amid Political Conflicts
BitPay Brings Apple Pay and Google Pay Checkout to Crypto Purchases
Four Security Strategies from the Wallet Theft Incident
Glassnode: Altcoin Trading Volume Returns to Normal Levels
Crypto: BlackRock Predicts Billions More in Its Crypto ETFs
Bakkt Aims for $6 Billion in Transaction Volume in Six Months, Doubling Annual Target; $10.4 Million Investment in Bitcoin Japan Recorded as of End of September
CoinShares: Data Center Ban Increases Value of Bitcoin Mining Companies' Power Assets
CoinShares: Data Center Ban Increases Value of Bitcoin Mining Companies' Power Assets
MARA Q3 Net Profit Rises to $632 Million, Sells 13,597 BTC in October to Repay Loans
Circle VP highlights AI agents driving demand for non-dollar stablecoins
Strive CIO advises BTC treasury firms on funding strategies
Barkin Highlights Inflation as Major Risk and Emphasizes Need for Cautious Monetary Policy Adjustment
Coldcard’s $116M exploit sparks fresh clash over NVK’s defense
The missing step in the warning that Japan could trigger Bitcoin’s next selloff
Two Bitcoin miners reported nearly $2 billion in profit. The biggest boost wasn’t cash
Super League buys 16 BTC for $1.23m as purchase sizes double
Bitcoin Lightning’s security update shuts one door. A critical Linux flaw remains
BlackRock: Bitcoin Whales Are Swapping Self-Custody For IBIT At Record Pace
Kraken Co-CEO Says Bitcoin Has Emerged from Bear Market
Aave DAO Supports Native BTC as Collateral for Aave V4 through Proposal
Bitcoin traders face an eight-hour blind spot as Deribit prepares to delay key market data
Can You Borrow Against Native Bitcoin (BTC) on Aave (AAVE) Yet? The Babylon Vote Explained
Can you borrow against native Bitcoin on Aave yet? See what the Babylon vote approved, what still needs to launch, and how BTC liquidation would work.
Kim & Chang Lawyer: "Excessive Responsibility Should Not Be Imposed on Stablecoin Issuers"
Mr&强 Analyzes Bitcoin and Ethereum Fluctuation Patterns
WEEX Exclusive:Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.
When is the launch date of Bitcoin Hyper? Testnet, tokens, and mainnet are separate milestones
Middle East Easing Expectations Boost Stocks | WEEX Daily Brief (November 10, 2026)
On November 9 close, the S&P 500 and Dow both rose more than 2%. Middle East easing expectations pushed oil prices lower. Bitcoin and Ethereum spot ETFs saw net outflows last week. AVAX rose on reports of tokenized-stock clearing. PIEVERSE surged short-term. November 10 focus is October CPI, TSMC monthly sales data, CoreWeave earnings and others.
Latest articles


Latest coin listings on WEEX


